
Which AI tool is best for retirement planning advice?
23 June, 1970
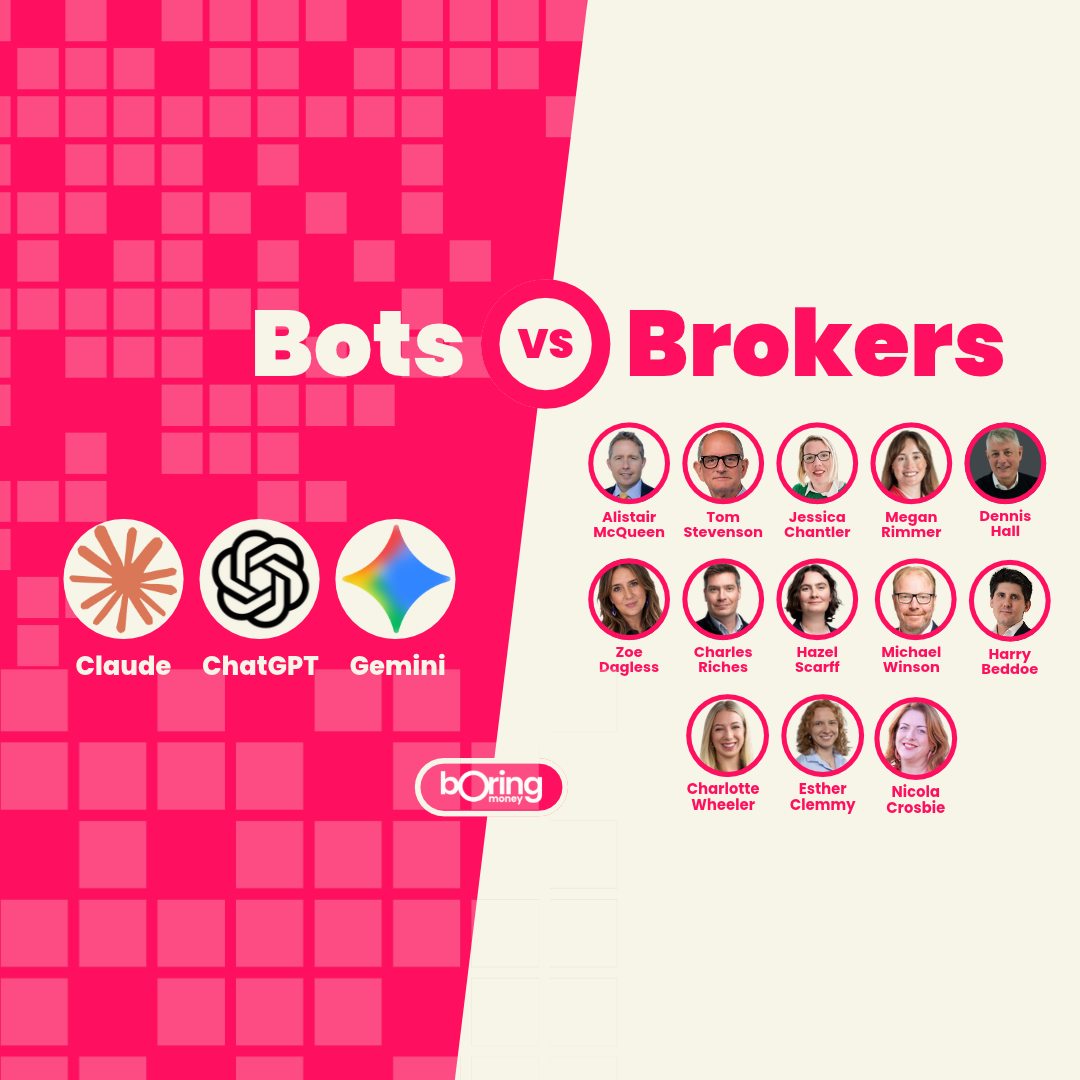
We asked Claude, ChatGPT and Gemini a real reader’s question about tax-free pension cash. Chartered financial planners marked their answers.
❓25% tax-free pension cash: is it better to take it as lump sums or draw down monthly amounts, paying tax on 75%?
This question was asked by a reader who has been investing for over 5 years but feels nervous about investing and is considering adding more defensive investments to their pension.
Marked by: Dennis Hall, Chartered Financial Planner, Yellowtail Financial Planning; Jessica Chantler, Chartered Financial Planner, Quilter; Charles Riches, Chartered Financial Planner, Capital; Hazel Scarff, Chartered Financial Planner, Capital
Neither is universally better; it depends on what you need the money for. The two routes are taking your full 25% tax-free cash upfront (with the rest going into drawdown, where withdrawals are taxed), or taking it gradually. With the gradual route, either through phased drawdown or UFPLS (uncrystallised funds pension lump sums), each withdrawal is 25% tax-free and 75% taxed.
Taking it all upfront makes sense if you have a specific use: paying off a mortgage, clearing debt, or a big purchase. It also locks in the tax-free entitlement, which some people value because the rules could change. But if it just sits in a savings account, it loses the tax-efficient pension wrapper and can be eroded by inflation.
Taking it gradually keeps more money invested inside the pension for longer. It also gives you a tax-free element every year, which can help keep your taxable income in a lower band. For many people who don’t need a lump sum, this is the more tax-efficient choice.
Since you’re nervous about markets, it’s worth knowing that moving cash out of the pension isn’t the only way to reduce risk. You can hold defensive assets, such as cash funds, gilts or bonds, inside the pension and keep the tax advantages.
Two other things to check: the tax-free amount is capped at £268,275 for most people, and unused pensions are due to fall within inheritance tax from April 2027.
I’m not a financial adviser. Pension Wise offers free, impartial guidance if you’re 50 or over, and a regulated adviser can model your specific situation.
Experts’ views
The response presupposes the investor can access tax-free cash. No age was given so it assumed. It (they) invented facts to fill the gaps and all read “nervous” to mean it needed to add defensive assets. Nothing in the question supports that view. No valuation, no other income, no other assets, no purpose for the money. Without these, every comment about and the £268,275 cap are potentially wrong (none mentioned whether any tax-free cash protection is in place).
It got a bit muddled when discussing phased drawdown mixing it with UFPLS (“each withdrawal is 25% tax-free, 75% taxed”) and lost the point that you can phase tax-free cash only, as a monthly income with no tax at all. It also omitted the Money Purchase Annual Allowance MPAA and they all missed the month-one emergency tax trap.
Dennis Hall
Grade: B-
Claude gives a clear explanation of the two broad options and provides a useful starting point without presenting either route as universally better.
It appropriately warns against withdrawing a lump sum without a clear purpose and then leaving it on deposit, where inflation could erode its purchasing power. It also usefully explains that investment risk can be reduced within the pension by holding more defensive assets, rather than assuming money must be withdrawn to make it safer.
There are high level mentions of aspects to consider but it doesn’t fully explain them. For example, it notes that 75% of gradual withdrawals may be taxable and that this can help manage tax bands, but it does not prompt consideration of the client’s other income, available allowances, or the possible effect of triggering the Money Purchase Annual Allowance.
It also mentions planned inheritance-tax changes from April 2027 as relevant but doesn’t make clear how those changes may affect the strategy in drawing from pensions, rather than using other assets, and recognising that this decision depends on the client’s wider estate and objectives.
The main weakness in this response is that it focuses on the mechanics of the two withdrawal options without prompting the client to consider their wider household position, retirement plans, existing assets and emotional response to drawing down capital. It also moves towards suggesting that gradual withdrawals may be more tax-efficient without first establishing the full facts.
Although the answer contains several helpful and broadly accurate points, it fails to deliver a response that could support a well-informed client decision.
Jessica Chantler
Grade: C
Claude starts in the right place: neither route is universally better and the purpose of the withdrawal matters. It explains clearly why taking the full lump sum without a specific need can be inefficient: money leaves the pension wrapper and may simply sit in cash while inflation erodes its real value. It also makes the useful point that a nervous investor does not need to withdraw from the pension simply to reduce risk. Cash, gilts and bonds can be held within the pension. It correctly flags the standard Lump Sum Allowance of £268,275 for most people, while acknowledging that individual protections can alter the position.
However, it does not first challenge the potentially contradictory wording of the question. The explanation of the gradual route is also too broad. UFPLS normally pays each withdrawal as 25% tax-free and 75% taxable, but phased flexi-access drawdown can operate differently: slices of the fund can be crystallised and the associated tax-free cash taken, while taxable drawdown is deferred or managed separately. It also assumes that the only relevant choice is between drawdown methods and does not explore whether guaranteed income through an annuity, or a blend of annuity and drawdown, could better meet the client’s needs.
Saying that “For many people…this is the more tax-efficient choice” is too confident without knowing age, earnings, State Pension and defined benefit income, other assets, planned spending, existing crystallisations, protection, residence and future pension contributions. The answer mentions inheritance tax reform, but does not turn that into a planning point. The client’s estate, beneficiaries and succession objectives would need to be understood before drawing a conclusion. In addition, it does not flag the MPAA. That matters if taxable flexible benefits are accessed and the client may continue making money purchase pension contributions.
If we were to receive this question from a client, we would first establish the spending need and timeframe, then quantify how much of the client’s essential expenditure is already covered by secure income. We’d obtain annuity quotations, including enhanced terms where health or lifestyle may be relevant, and compare full drawdown with annuity and hybrid solutions.If there is no immediate purpose for a large lump sum, we would usually avoid taking it merely because it is available. We would then model the client’s income year by year, coordinate withdrawals with their tax bands and use cash or short-dated defensive assets inside the pension to fund near-term spending. The withdrawal method would follow the plan, not lead it.
Charles Riches and Hazel Scarff
Grade: B-
The choice between taking your 25% tax-free pension cash as a lump sum or in stages depends on your income, how much you need to spend and what you want to do with the money. If you are a cautious investor and want to add defensive assets to your portfolio, it is worth considering how each option fits your wider retirement plan.
Taking a lump sum gives you immediate access to cash, which could be useful for paying off debt, covering a large expense or building an emergency fund. However, taking the full amount unnecessarily could leave you holding more cash than you need, potentially losing purchasing power to inflation. You would also need to decide where to invest any surplus.
Taking tax-free cash in stages can spread the benefit over time and leave more money invested within your pension, where it can continue to grow tax-free. Depending on how you access your pension, you may be able to take 25% of each withdrawal tax-free, with the remaining 75% subject to income tax. This can help manage your taxable income in retirement, particularly if you are trying to avoid moving into a higher tax band.
For a nervous investor, taking the money gradually may feel more manageable, particularly if you do not need a large sum immediately. You could also keep some money in cash for short-term spending while maintaining a diversified portfolio for longer-term needs.
The key is to avoid taking more taxable income than necessary in a single tax year. Remember, most people can take up to £268,275 in tax-free pension cash across their pensions, subject to their available allowance.
Before deciding, check your expected retirement income, tax band, withdrawal fees and whether accessing taxable pension money would trigger the Money Purchase Annual Allowance, reducing how much you can contribute to a pension while receiving tax relief.
In short: if you do not need the cash now, phased withdrawals may offer greater flexibility and help manage tax. Consider speaking to Pension Wise or a regulated financial adviser before making an irreversible decision.
Experts’ views
It had the cleanest technical record (MPAA correctly outlined), which was its case for potentially giving it a B. But because its entire answer is built on unexamined assumptions, I dropped it to a C.
It opens by restating the questioner’s framing as given: “a cautious investor” wanting defensive assets as though that described the current portfolio, and it never asks for a single fact needed for the stated generalities to become advice.
It gave vague answers based on the premise it assumed (no mention of UFPLS or Phased Drawdown), so possibly worse than the other two options, which were more specific, though still flawed. It seems to read in a nice informative and friendly way, but there’s no real substance. It would be easier to drill down Claude and Gemini because there are some specifics to latch on to, driving additional questions.
Dennis Hall
Grade: B-
Overall, this is a reasonably comprehensive answer that provides a helpful starting point for the client. It explains the two broad options clearly and, importantly, encourages consideration of the client’s wider financial circumstances and the purpose of any withdrawal rather than treating the decision as purely technical.
The practical guidance is useful, particularly the prompts to review expected retirement income, tax bands, withdrawal charges and whether the client actually needs capital or income. It also appropriately warns against taking more taxable income than necessary and recognises that a nervous investor may value a gradual, flexible approach.
The answer also raises the Money Purchase Annual Allowance (MPAA), which is relevant if the client may continue contributing to a pension. However, the explanation should be more explicit: accessing taxable pension income flexibly will trigger the MPAA, whereas taking only tax-free cash will not. This distinction matters and should be stated more clearly.
Its main weakness is the lack of prompting the client to consider the emotional and behavioural aspect of this decision. Will they feel uncomfortable seeing their pension value reduce?
It also concludes that phased withdrawals may be preferable where there is no immediate need for cash. Although this may be a reasonable outcome in some cases, it moves too close to a recommendation before the client’s full circumstances, objectives and wider household position have been established.
Jessica Chantler
Grade: C
In terms of positives, ChatGPT frames the decision around income, spending and the intended use of the money, rather than treating tax-free cash as an automatic entitlement to be taken immediately. It’s careful to say that 25% of each withdrawal “may” be tax-free depending on the access method, which is more precise than treating all phased drawdown as identical to UFPLS.
It highlights several practical issues that genuinely affect the decision: tax bands, withdrawal charges, inflation, surplus cash and the MPAA, and gives a sensible high-level conclusion: if the cash is not needed now, staged withdrawals can preserve flexibility and support tax management.
However, it does not explicitly clarify that the 75% taxable element relates to the overall withdrawal, not to the 25% tax-free cash itself. The investor’s nervousness is also allowed to influence the withdrawal method rather too directly. Risk appetite should shape the underlying investment and cashflow strategy, not automatically determine how pension benefits are crystallised. It also accepts the drawdown framing without testing whether an annuity should be modelled, despite the apparent concern about investment risk.
“Taking the money gradually may feel more manageable” is psychologically plausible but not necessarily financially relevant. A nervous client could be reassured by a properly segmented cashflow plan without withdrawing assets from the pension wrapper. The answer should distinguish more clearly between taking tax-free cash and taking taxable income. Taking tax-free cash alone does not normally trigger the MPAA; accessing taxable flexible income generally does. It omits estate planning, death-benefit nominations, health and longevity, spouse or partner income, State Pension timing and whether tax-free cash has already been used from other schemes.
This is closest to our own approach, but it still starts too far downstream. Before choosing a drawdown method, we would test whether guaranteed income is needed and obtain annuity quotations alongside the drawdown modelling.We’d keep the core of the answer, but put a cashflow plan around it. We’d then establish the client’s essential and discretionary spending, other secure income and cash reserves, then compare full tax-free cash, phased crystallisation and UFPLS over several tax years. The recommendation would be based on lifetime tax and flexibility, not simply the tax charge on the next withdrawal.
Charles Riches and Hazel Scarff
Grade: B-
Neither option is universally "better"—it depends on your tax band, other income, and how you manage nervousness.
Lump Sums vs. Monthly Drawdown
- Taking lump sums (e.g., UFPLS): You pull chunks of cash as needed. The first 25% of each chunk is tax-free, and the remaining 75% is taxed as income. Taking large sums at once can push you into a higher income tax bracket for that year. It also triggers the Money Purchase Annual Allowance (MPAA), which cuts future tax-free pension contributions to £10,000 a year if you are still working.
- Monthly drawdown: You move your pot into flexible drawdown, take your 25% tax-free cash (either all at once or in staged parts), and draw regular taxable income from the remaining 75%. Spreading regular income helps you stay within your Personal Allowance (£12,570) or lower tax band.
Key Considerations for Your Situation
- Nervousness & Markets: Withdrawing large lump sums or taking money out immediately after market dips locks in losses. Keeping the bulk invested in your current strategy—while shifting a portion to defensive assets—allows remaining funds to keep working.
- Leaving cash in the pot: Money left invested inside a pension continues to grow tax-free and currently sits outside your estate for Inheritance Tax (though rule changes are planned from April 2027). Taking everything out early strips away future growth.
To help tailor this to your plans, could you share:
- Your approximate annual income (from work, State Pension, or other sources)?
- How much money you are thinking of withdrawing each month or year?
I can give you a clearer idea of how the tax bands might affect you.
Experts’ views
There’s no eligibility check, no request for age or pot size, and it anchored the nervousness to market behaviour (“selling after dips locks in losses”) without knowing how the pension is invested.
Its partial redemption is that it was the only one to ask for missing facts at the end, which is the closest any of them came to an adviser’s instinct to ask for more information; but it skipped the questions that gate the whole exercise (age, valuation, other assets, purpose).
It also included some sloppy MPAA wording, which implies any lump sum triggers it.
Dennis Hall
Grade: B-
For a reader with limited financial knowledge, the opening section of this answer is likely to be confusing. It labels the lump-sum option as “UFPLS” without explaining the term, even though UFPLS can also be used to provide regular withdrawals. It then presents “monthly drawdown” through an example in which all tax-free cash has already been taken as a lump sum. This distinction is unclear and is unlikely to leave the reader feeling confident about the options available.
The reference to how the client might “manage nervousness” hints at a more rounded answer, but the point is not developed into meaningful or thought-provoking guidance. When the response returns to risk later, it focuses on measurable factors such as market movements and inflation rather than exploring the client’s feelings, behaviour and tolerance for seeing their pension value fall during retirement.
The response gives too little attention to why the client needs the money, what other assets and income they have, and which priorities should shape the decision. Instead, it moves too quickly into technical detail and presents that detail in a way that may add confusion rather than support an informed choice.
The offer to tailor the response if the client provides more information is helpful. However, this also highlights the limitations of the initial answer: without that wider context, the reader is unlikely to have enough clear, relevant information to make a well-informed decision.
Jessica Chantler
Grade: C
Gemini correctly identifies annual income and the intended withdrawal amount as essential missing information, and asks for both before attempting a more tailored answer.
It also explains that large taxable withdrawals can push income into a higher tax band and that pension assets can remain invested in defensive holdings and recognises the relevance of the MPAA and the planned inheritance tax changes affecting unused pension funds from April 2027.
However, it does not resolve the ambiguity in the original question and it blurs the two routes. “Taking lump sums” is presented as UFPLS, but a lump sum could also mean taking pension commencement lump sum tax-free cash without taking taxable income. Those routes can have different tax and MPAA consequences. It also fails to consider guaranteed income through an annuity as an alternative to, or complement to, drawdown.
The phrase “future tax-free pension contributions” is inaccurate. The MPAA restricts the amount that can be contributed to money purchase pensions with tax relief without an annual allowance charge; it does not mean only £10,000 can be contributed, nor that the contributions themselves are “tax-free”.
There are several other elements of its response that should sound alarm bells to an adviser. “Withdrawing…after market dips locks in losses” is too sweeping. Losses are crystallised if investments are sold to fund the withdrawal. A planned cash reserve or sale of a different asset can change the position. “Taking everything out early strips away future growth” overstates the point. Money taken out can still grow elsewhere, although it may lose the pension’s tax treatment and estate-planning characteristics.
The answer asks two good questions, but still needs age, employment status, future contribution plans, existing pension access, other pensions and assets, spending objectives, household tax position and health or longevity considerations.
In this situation, we would slow the conversation down and separate four decisions: whether to take any tax-free cash, whether to secure some guaranteed income through an annuity, whether to draw taxable income, and how the remaining fund should be invested. Those decisions are related, but they are not the same. Only after mapping the client’s objectives, household cashflow, secure income needs and tolerance for investment risk would I compare annuity purchase, phased crystallisation, UFPLS and flexi-access drawdown.
Charles Riches and Hazel Scarff
Grade: C
The scores
Adviser | Claude (average C+) | ChatGPT (B-) | Gemini (average C+) |
Dennis | B- | C | B- |
Jessica | C | B | C |
Charles and Hazel | B- | B- | C |
What the experts want you to know
The bots made assumptions without the right information. They assumed the reader was fully invested and worried about sequencing risk (how you balance what you withdraw with how the rest is invested). How you feel is not a good proxy for how you should invest. You might feel nervous, but your circumstances might mean you can afford to ride out the ups and downs, so more defensive investments may not be right for you.
Dennis Hall
The bots didn’t pick up on the emotional side of the question, or press for the extra context an adviser would ask for first, like why you actually need the money and what else is going on in your finances. They jumped into technical detail that can overload and confuse, rather than help you make a better decision.
Jessica Chantler
The bots skipped a step by assuming drawdown was the answer and only debating which version to use. None of them stopped to ask whether some or all of the pension could instead buy a guaranteed income through an annuity (a product that pays you a set income for life), which deserves a fresh look now that annuity rates have improved. Also, the bots let the reader’s nervousness steer how the money should be taken out, when really it should shape how the remaining money is invested. The missing information (what the money is for, essential spending, other secure income and wider tax position) mattered far more than the mechanics of each option.
Charles Riches and Hazel Scarff
If you’re using AI tools for questions on retirement planning, especially tax-free cash, make sure you:
- Specify your age.
- Even if you feel nervous, tell the AI tool not to make assumptions about your asset allocation based on your feelings alone.
- Give the AI some information about your timeframes for the investments and / or pension.
- Say when you need the pension money and what it’s for.
- Ask the tool to be specific about UFPLS, and to be clear about phasing the tax-free cash only.
- Ask the tool to include the MPAA (Money Purchase Annual Allowance) and explain the impact it has.
- Give relevant information about any spouse or partner, and your financial position as a couple.
- Be careful about uploading personal information if you don’t pay for the tool and it isn’t private or secure.
Retirement planning and pensions can be complex. Look into one-off advice, or pay for a sense-check, if you can.
———-
[1] Boring Money
[2] Fidelity
[3] 2020financial
[4] Peoples Pension
[5] Royal London
[6] Fidelity
[7] AJ Bell
[8] Boring Money
[9] Fidelity
[10] Fidelity
[11] Rathbones
[12] Fidelity