
Give me some advice, Claude?
By Holly Mackay, Founder & CEO
9 Oct, 2026
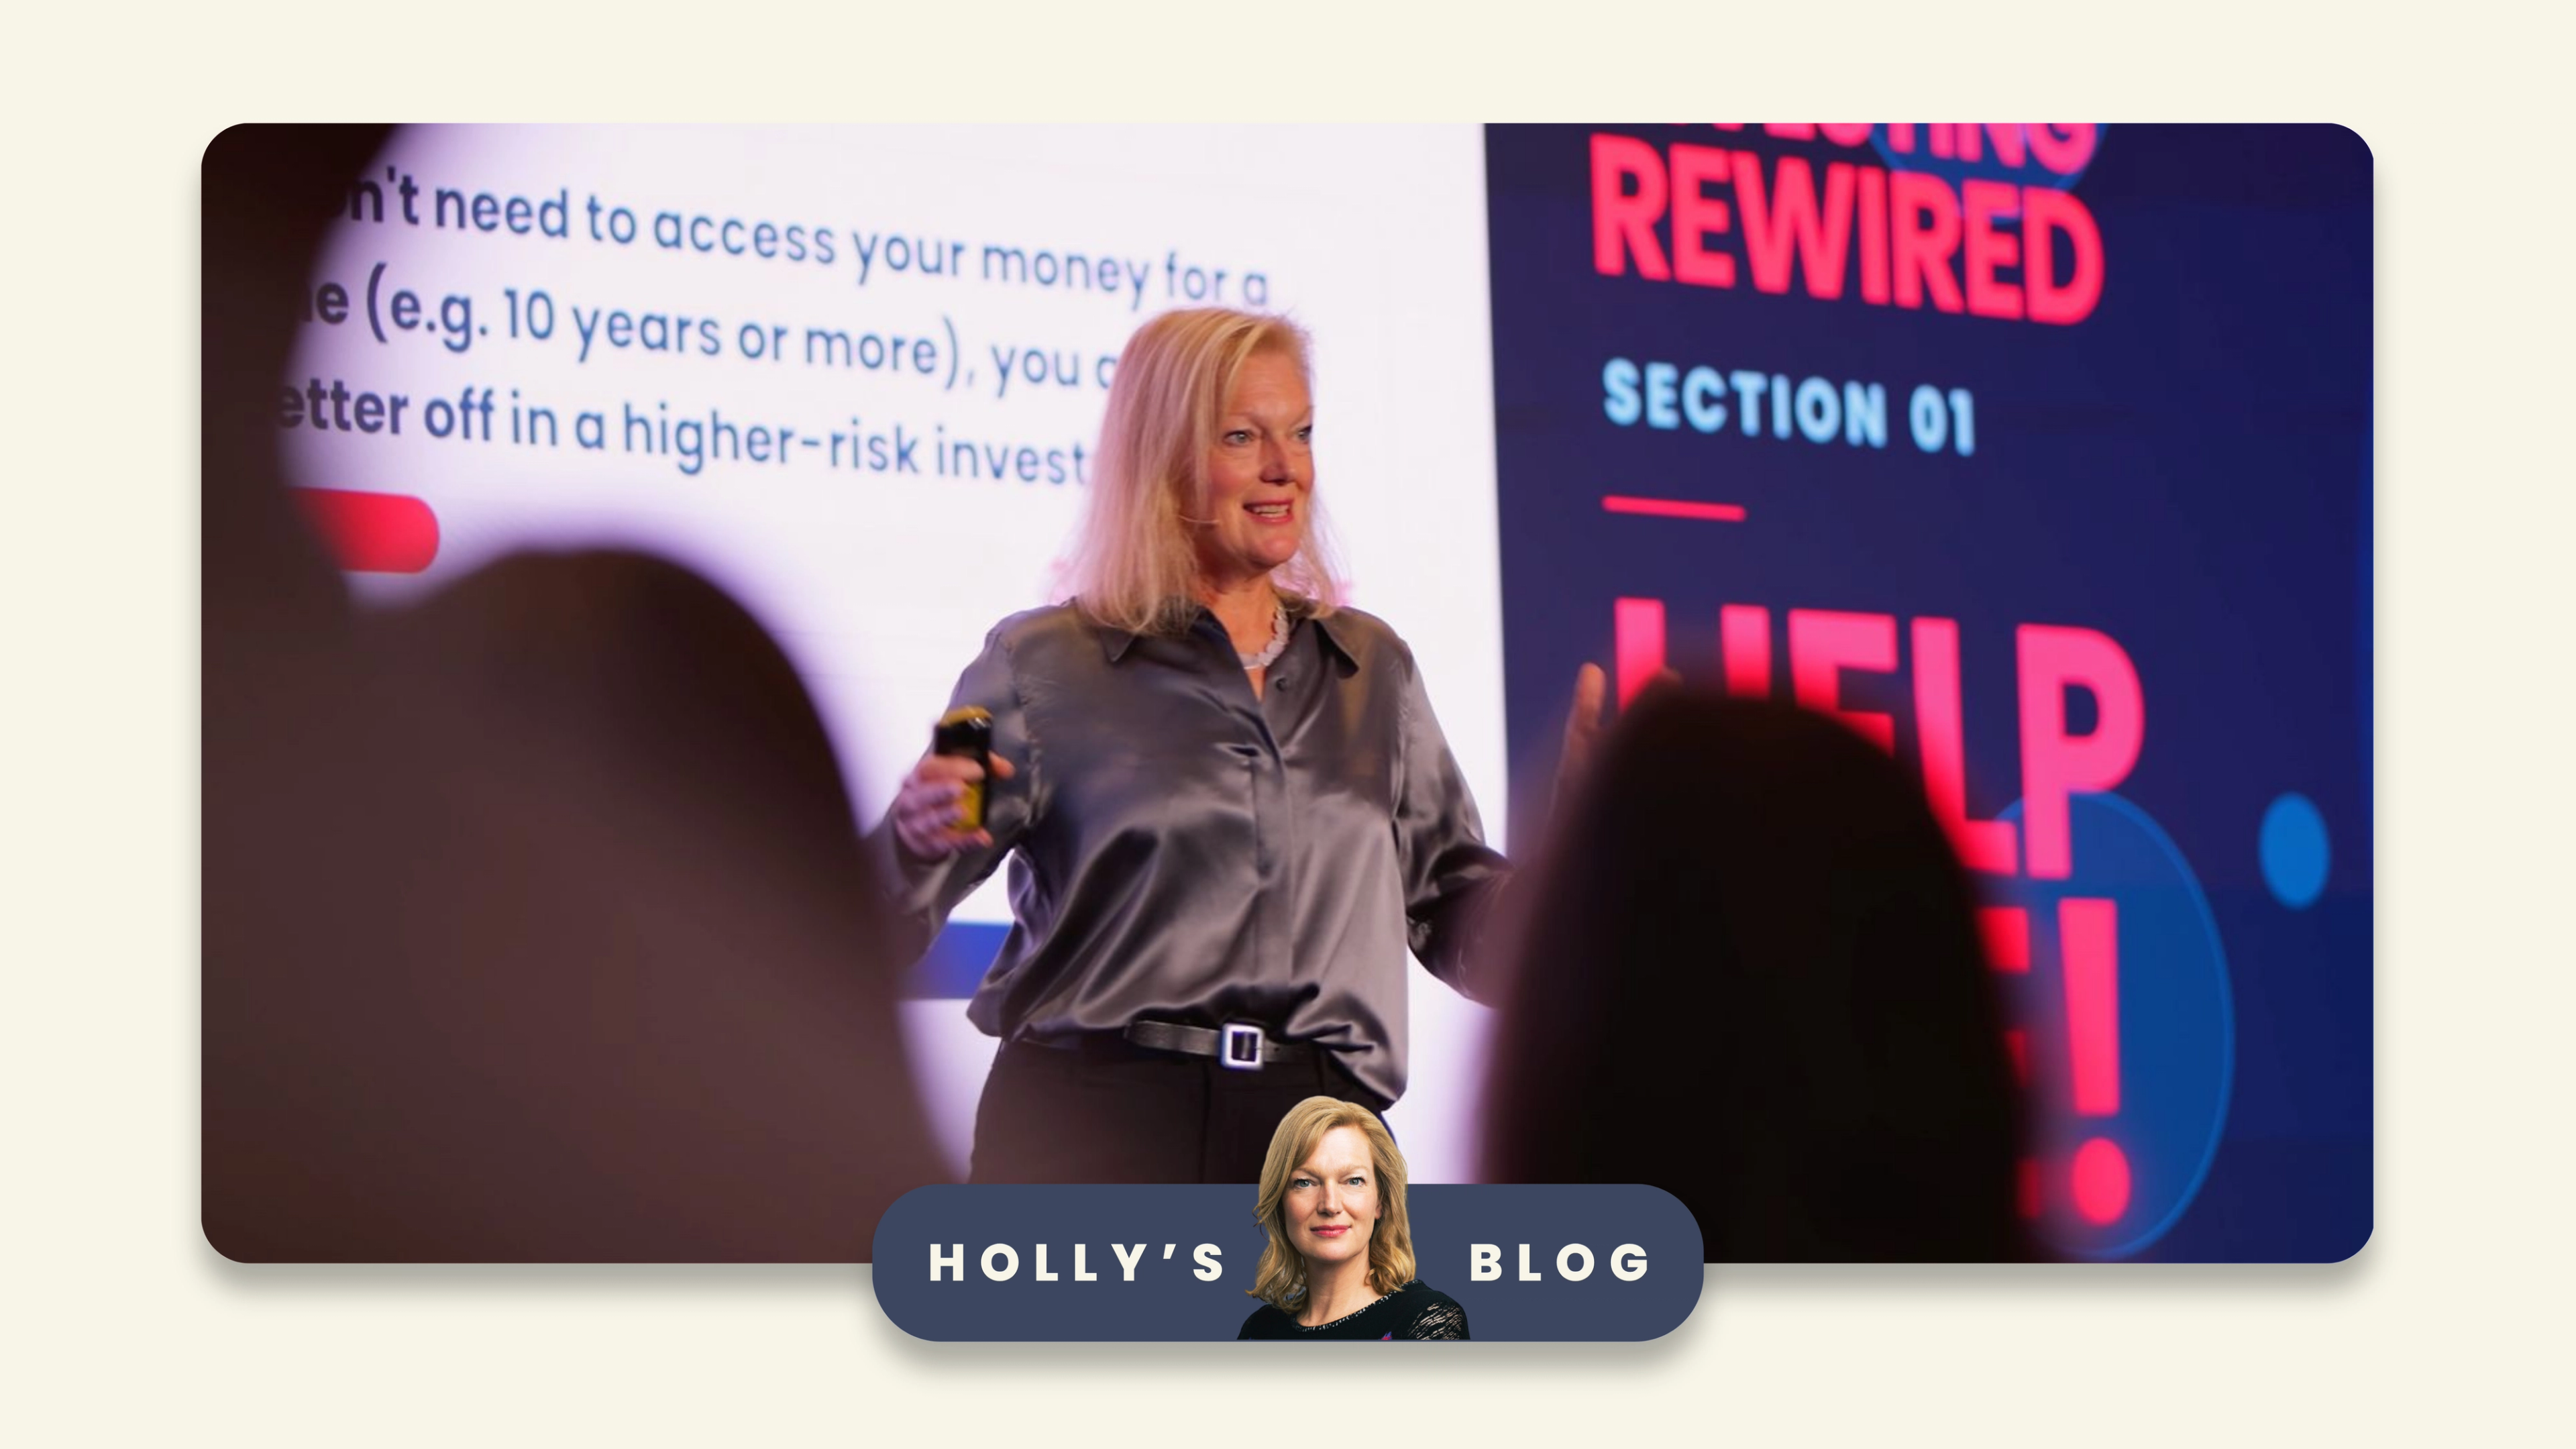
This week I chaired our annual conference in London and welcomed the CEOs of Quilter, Barclays Private Bank, J.P. Morgan Personal Investing and others to join us as we looked at how regulation and tech were changing and what we can make and deliver to customers.
AI is rapidly becoming more widely adopted as people sense-check financial information with Claude, Gemini and the gang. One-third of DIY investors are now using AI for financial help and information.
It’s not just self-directed investors either. Our research finds that 45% of advised clients with over £1 million in assets are also using AI for financial information and advice. Sometimes sense-checking what their adviser has said, or even helping them to prepare for a meeting.
But is AI any good for this stuff?
I think its capability depends on what you’re asking for. If you want product information or technical facts, it’s pretty good. And we can put some protections in place to stop it from being silly. I ask any LLM to cite its sources and justify its claims. I also direct it to credible sources and sites – you might tell it to use Boring Money, Morningstar, big name fund managers, Aviva, L&G, HMRC or financial advice firms for example.
Here’s a made-up scenario. I told Claude I earned £68,000, and had 2 children and was a higher rate taxpayer. What did I have to pay into a pension to get my income down to still get full child benefit? (Because paying into a pension brings your income down for tax purposes = cunning!)
I got a pretty good answer. If I have a personal pension, I pay in £6,400. The pension company immediately pays in another 20% ‘at source’ to make it up to £8,000. And then (because I’m a higher rate taxpayer) I claim the further 20% when I file a tax return.
This gets my “adjusted net income” down to £60,000. I get full child benefit. I get a top-up in my pension. AND I get to file a tax return which tells HMRC they need to refund me some more tax as I’m a higher rate taxpayer. Yay. The only good brown envelope you will ever see.
Now here’s the important bit
I then asked Claude to check its workings using HMRC, Aviva, Legal & General and Hargreaves Lansdown. All pretty good on pension stuff. I got more information back and a tick list of key assumptions and inputs used, corroborated and sourced.
So far so good. However, as soon as the picture gets more complex, it becomes less good and can often be wrong. And Claude doesn’t know what you haven’t told it. I then typed in “My husband earns £80,000.” And Claude went into a tailspin.
AI is a wonderful partner in answering questions, but I don’t rely on it. I think it can really help for many financial questions BUT you have to know what to ask. And it won’t prompt you to tell it all the required inputs. I think it’s always a good idea to ask the AI what factors might change its answer. And for now, I don’t think it is in any way a substitute for good financial planning.
Claude knows a lot about me. I ask Claude things I wouldn’t be seen dead asking anyone else, but my search history is not going to thrill any spying Chinese General. The last 10 questions include 10-year bond yields, false eyelashes (not mine!), synthetic data, biryani and phosphorescence. So, I love Claudius Maximus. But only for some things. (Since you ask I have never once used AI to write my blog and I wouldn’t. It’s rubbish at jokes, even worse than me. And it doesn’t know how to talk about stock markets, the Traitors and the teenagers in the same paragraph. Pah! Loser.)
Another important note here. Be very careful about what you feed into free AI tools and be aware of where you are sharing your personal data and documents. Financial scams are rife and they are complex and they can catch us all, however savvy we think we are.
5 tips
We heard from an AI expert and futurist at the event and I asked him about the pace of change. How soon, I wondered, until we trust AI with really “hardcore hairy stuff” like Inheritance Tax planning. His answer? “I would say within the next two years, you'll see products out there that will do things on a personal level, and the AI will be smart enough to run on a mobile phone or a laptop and not have to run in the cloud." Wow.
For now, I’ll leave you with his 4 top tips to up your digital game:
- Ask an AI to recommend providers – but make it work harder and justify why
- Professionals – ask an AI to review a customer document or recommendation and critique you
- Professionals - compare an AI’s answers with yours – what can you learn from it?
- Buy an AI savvy friend lunch – learn from them.”
He also told me to get Claude to interview me. Oh God. I did make a start…... The first question. “If Boring Money didn’t exist, who would miss it most?” That has prompted an existential crisis and a bout of acute imposter syndrome and self-criticism. If I were American I would shout, “Great question! Kudos to you!” But I’m English so I logged off, muttered “Smartarse” and am going to have a cup of very analogue tea instead!
What the video below for highlights from this year’s conference.
Have a great weekend, everyone.
Holly
The views expressed in this blog are Holly Mackay’s own and do not constitute regulated financial advice. If in doubt, always seek the help of a professional financial adviser before making decisions with your money.
Post a comment:
This is an open discussion and does not represent the views of Boring Money. We want our communities to be welcoming and helpful. Spam, personal attacks and offensive language will not be tolerated. Posts may be deleted and repeat offenders blocked at our discretion.
Your opinion matters
Be the first to comment.